Research
I build stochastic models that follow shocks from firms to the banks and insurers exposed to them: cyber epidemics through insurance portfolios, carbon prices and warming through credit portfolios, and order flow through prices.
Cyber Risk
How attacks spread between firms, and what they cost insurers and defenders.
\[Y_t=\frac{1}{N_0}\sum_{k=1}^{K}\beta_{k,t}\,kI_{k,t}\]Force of infection of the cyber epidemic
Climate Risk
How the carbon price and global warming reach firms, collateral and banks.
\[\bar c^{\,i}_t=\big(\omega^i_t+r^i_t+y^i_t\,\delta_t\big)\,e^{\gamma(T_t-T_0)}\]Effective cost per unit of output: raised by warming and by the carbon price
Market Microstructure
How order flow, liquidity and trading strategies shape prices in limit order books.
\[r_t=S_t-q_t\,\gamma\,\sigma^2\,(T-t)\]Market maker’s reservation price
News
- Upcoming talk at Mathematical Advances on Emerging Risks 2026 in Mexico City, on a major–minor mean-field game for optimal cybersecurity investment.
- Our paper with Caroline Hillairet and Olivier Lopez, A stochastic SIR model for cyber contagion, is published in the Scandinavian Actuarial Journal.
- Presented our cyber-contagion SIR model at the 7th European Actuarial Journal Conference in Istanbul (slides).
- Joined CEMRACS 2026 at CIRM Marseille to build a dynamic top-down model for losses under climate, credit and market risks.
- New preprint with Caroline Hillairet and Olivier Lopez: A stochastic SIR model for cyber contagion.
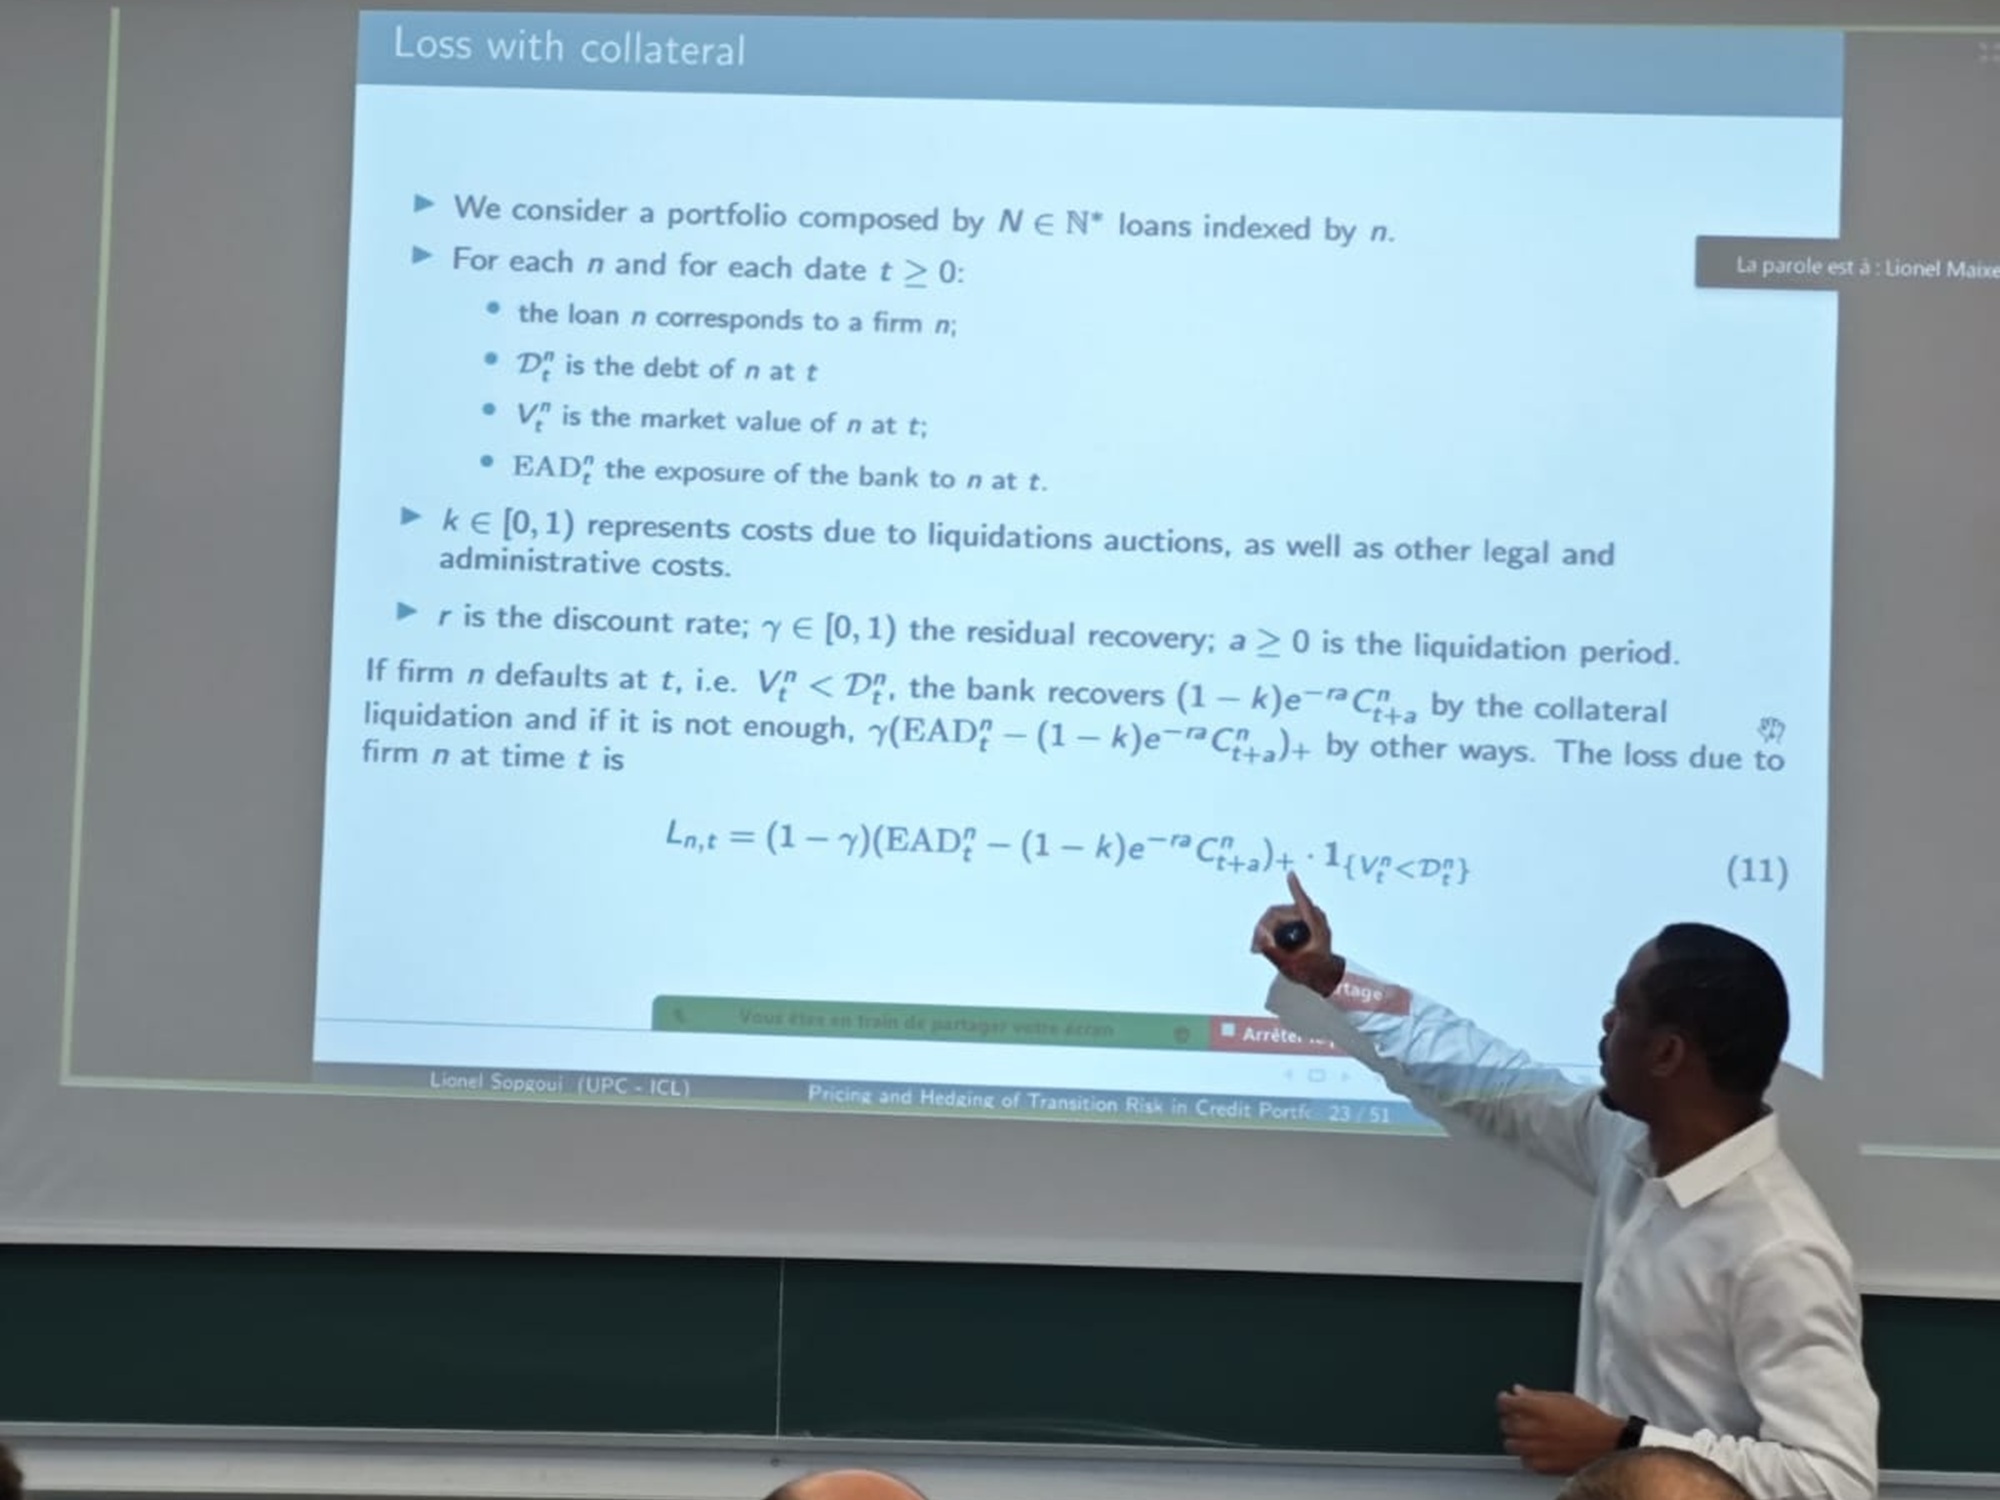
- Published in Quantitative Finance: Impact of the carbon price on credit portfolio’s loss with stochastic collateral.
Recent publications
- Climate-vulnerable firms, credit supply, and cascading failures: an agent-based modelPreprintClimate Transition Risk
- Modeling the impact of climate transition on real estate pricesPreprintClimate Transition Risk
- A stochastic SIR model for cyber contagion: application to granular growth of firms and to insurance portfolioCyber Risk
- Impact of the carbon price on credit portfolio’s loss with stochastic collateralClimate Transition Risk
- Propagation of a carbon price in a credit portfolio through macroeconomic factorsClimate Transition Risk